optra
Health Gecti
- License — License: NOASSERTION
- Description — Repository has a description
- Active repo — Last push 0 days ago
- Community trust — 21 GitHub stars
Code Gecti
- Code scan — Scanned 12 files during light audit, no dangerous patterns found
Permissions Gecti
- Permissions — No dangerous permissions requested
Bu listing icin henuz AI raporu yok.
Options trading and research system in C++23: one event-driven engine for backtest and live trading on Interactive Brokers, a quant lab on the same data, and MCP tools for AI agents.
Optra
Options trading and analytics, in C++23.
One event-driven engine for backtesting and live trading on Interactive Brokers, research tools on the same data, and one API an AI agent can drive.

Live demo · Architecture · Documentation · 中文
What is in it
| Engine | Strategies take events (timer, snapshot, order, fill) and emit orders; the same code runs a deterministic backtest over Parquet days and trades live through IB, in one process with a single writer thread. Multi-leg combos, implied vol and Greeks on each expiry's parity forward, settlement at expiry, per-strategy delta hedging, a pre-trade risk check, P&L attribution by Greeks. |
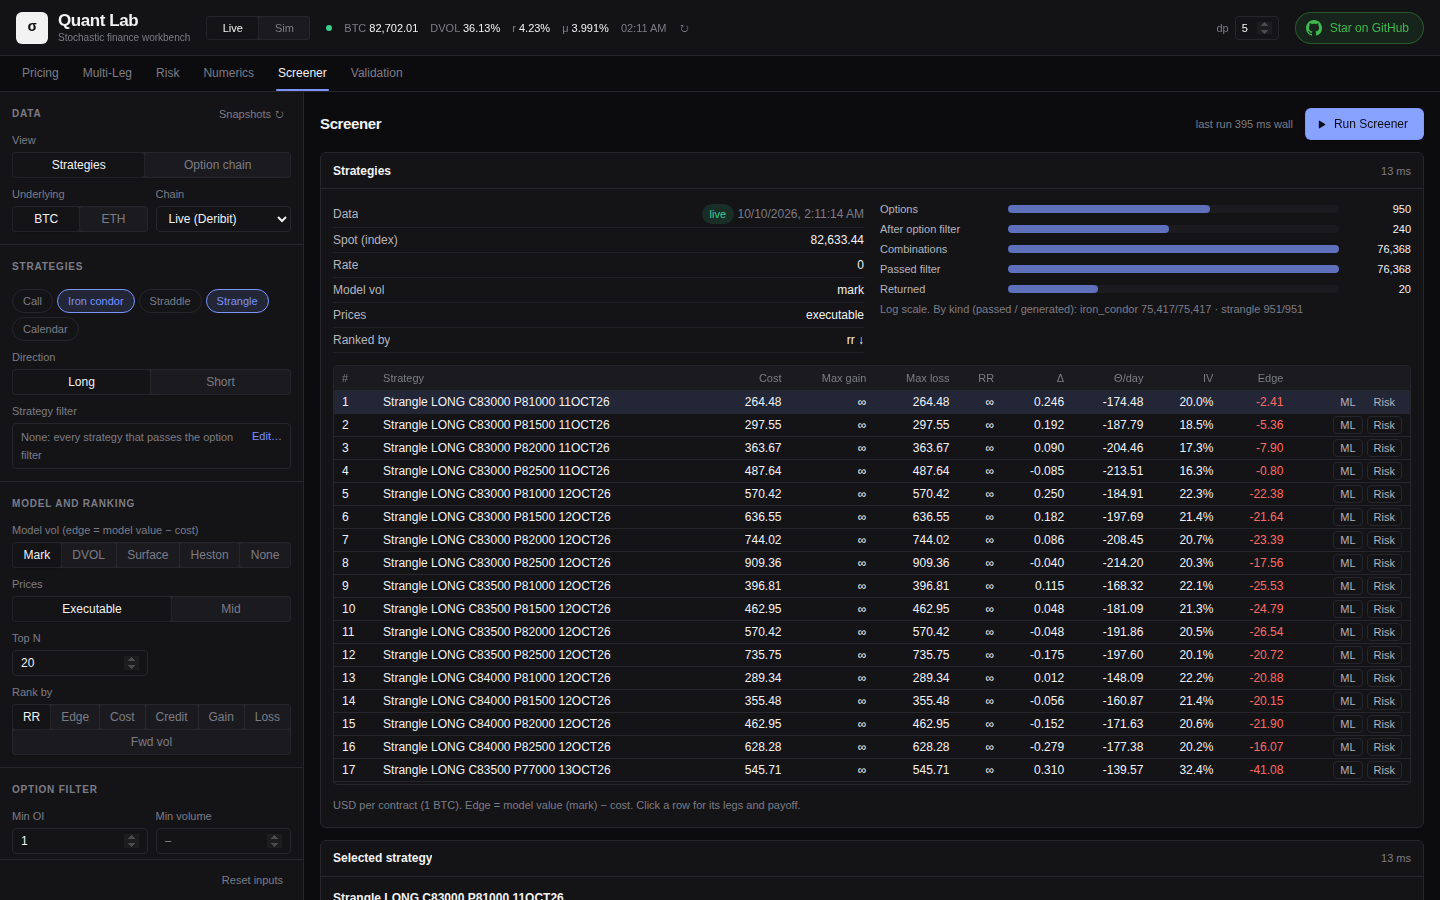
| Research tools | Pricing (Black-Scholes, Monte Carlo, trees, PDE, Heston), calibration, stress packs, hedging studies and an options screener, on the engine's own numerics and its backtest and recorded days. |
| Research loop | A combo picked in the screener is backtested as a rule over every day, broken down by Greek, compared hedged and unhedged, and added to the paper account with the setting it was tested with. |
| Agent tools | Every capability is a declared tool with a described input schema and one result envelope, over HTTP and from Python; every run is kept for comparison. No tool places an order. |
Quick start
Linux, GCC 14 or newer (Ubuntu 26.04 is the reference):
sudo apt install g++ cmake make libarrow-dev libparquet-dev libprotobuf-dev protobuf-compiler libgrpc++-dev \
  protobuf-compiler-grpc libabsl-dev nlohmann-json3-dev libsqlite3-dev libgtest-dev 7zip

./build.sh r                     # engine/build: entry_backtest, entry_live, entry_simulate, libanalytics_c.so

# synthetic days from a model whose answers are known (no data ships with the repository)
uv run --project app/server python scripts/data/synthetic_to_parquet.py \
  --start 2025-03-03 --end 2025-03-07 --out data --symbol SPY

# a straddle each day, with its P&L split by delta, gamma, theta, vega
./engine/build/entry_backtest --files data/SPY/SPY-2025-03/*.parquet ComboStrategy \
  leg1_ratio=1 leg2_ratio=1 leg2_right=1

./scripts/dev.sh                 # the server and the page at http://localhost:5173
entry_backtest --list-strategies lists the strategies and their parameters. A backtest needs no network and no database.
How it works
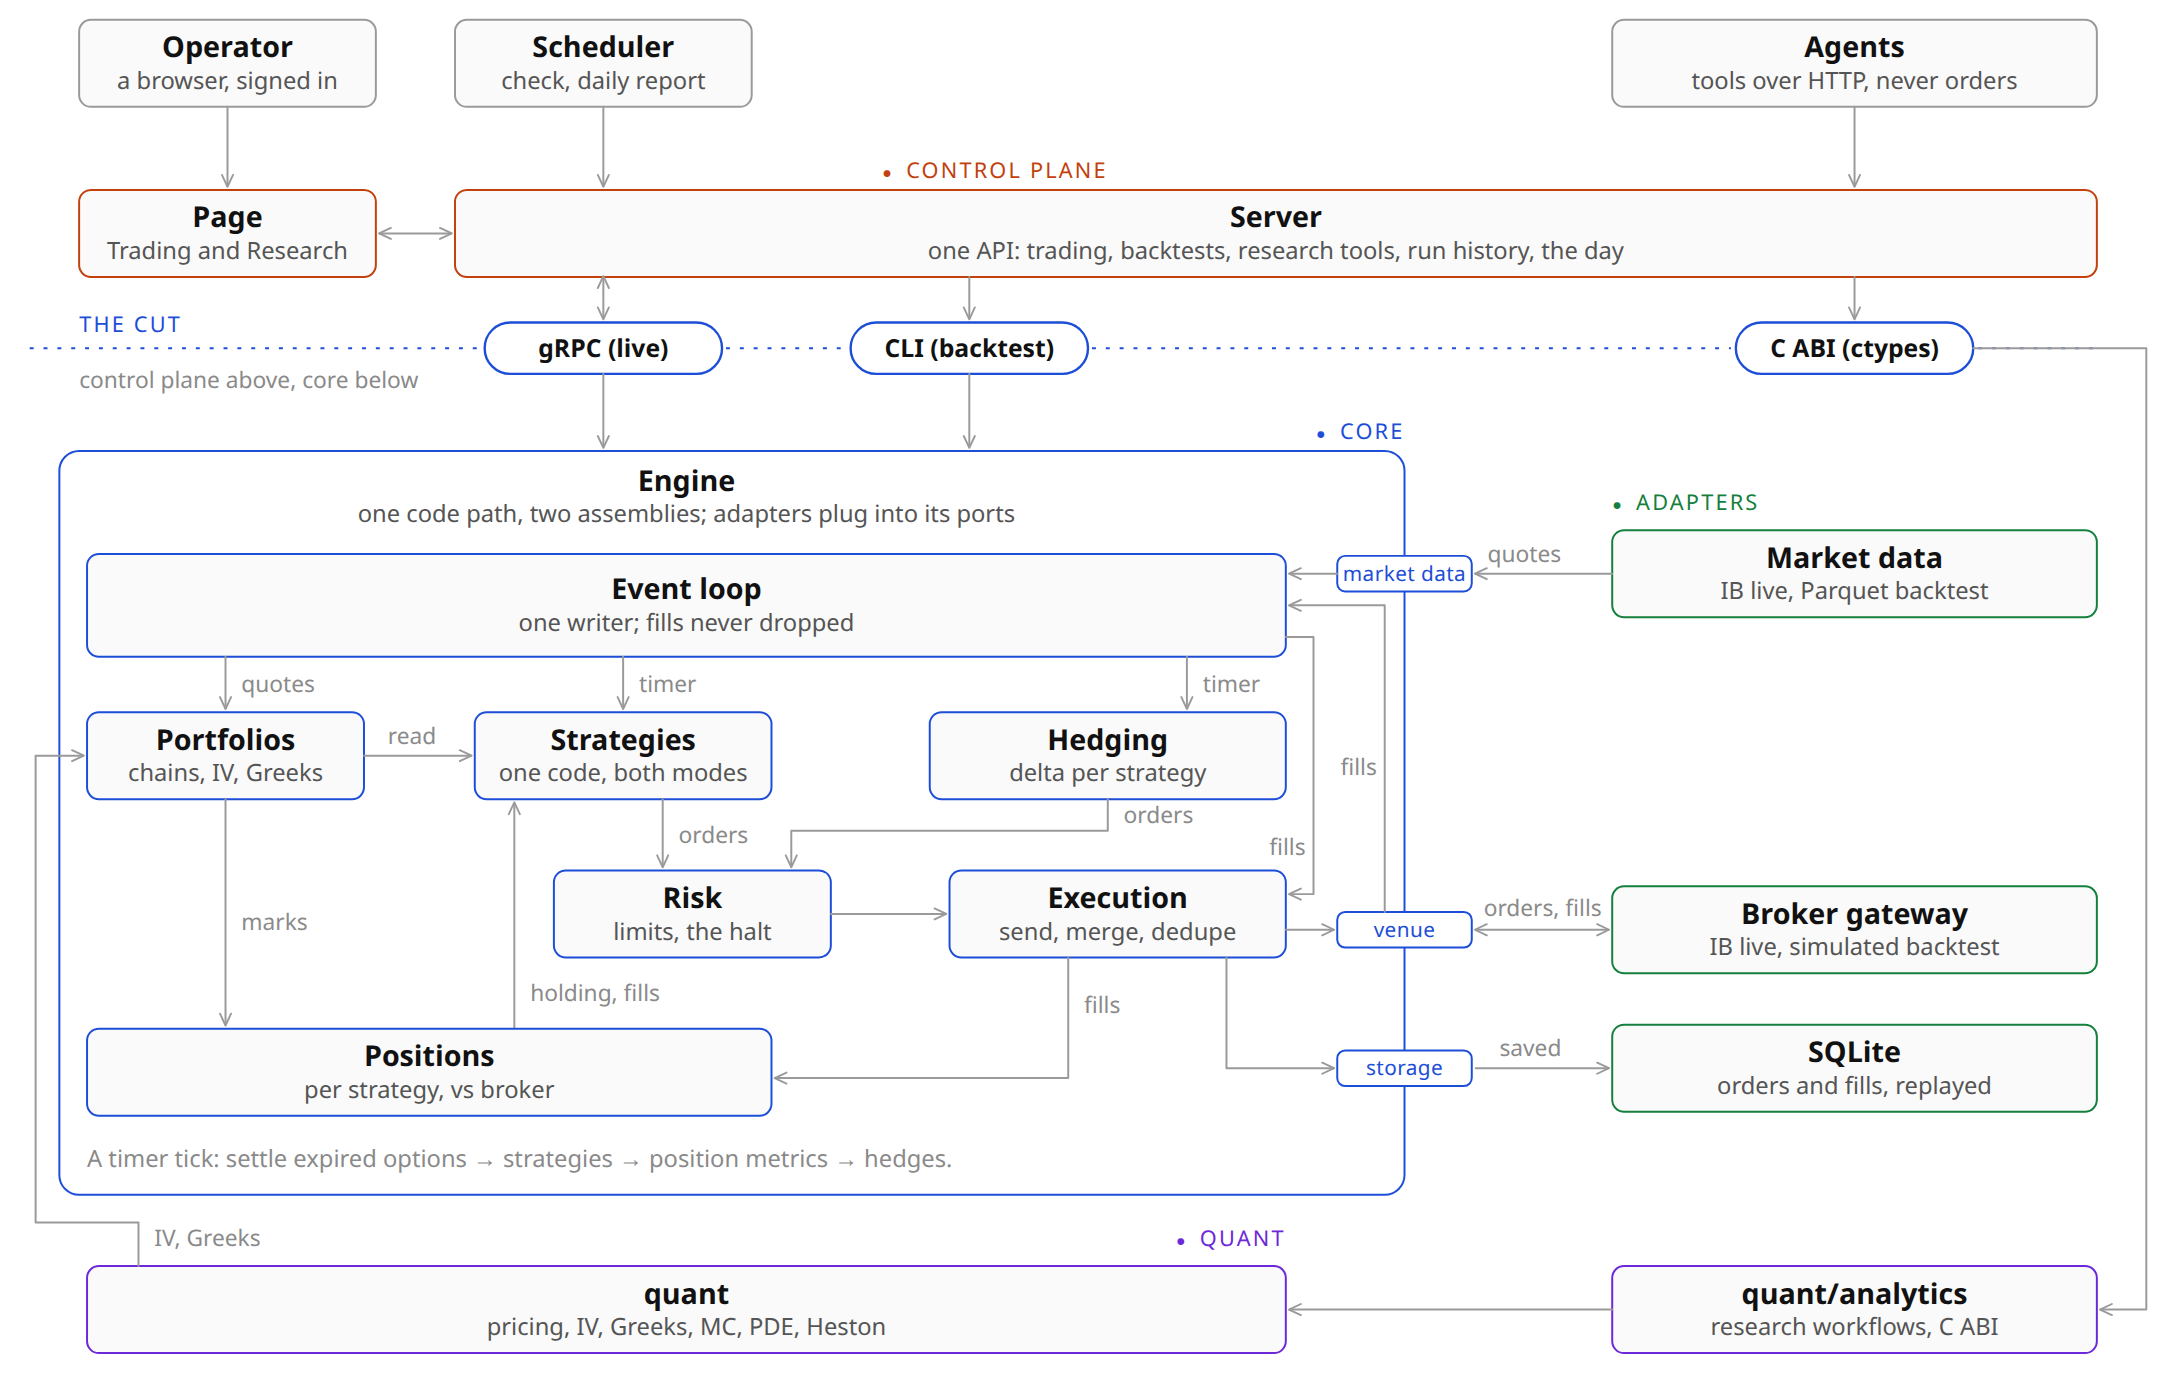
In the diagram at the top: above the cut at gRPC, the control plane (the page and the server) only asks; below it, the engine owns the trading state and reaches the outside through adapters plugged into its ports (market data, venue, storage); the numerics are one library for the engine and the server's research tools. Booking is deterministic: a fill is one contract's, order updates are merged and an order's end waits for its fills, so the holding never depends on the order the broker reports in. A restart rebooks every saved fill and checks the holdings against the broker before any strategy starts. The full design: architecture, and the interactive diagram (click a box for what it does).
Live trading
Optra runs every trading day on an IBKR paper account: contracts synced before the open, a health check every five minutes, and a report after the close that replays the recorded day in a backtest and lines the paper fills up against it. The engine trades one named account and refuses a live one unless root allows it. The live demo runs the same engine on a simulated account (entry_simulate: synthetic days replayed as the market, no broker). What IB sends for each order and how it is booked: IB orders and fills.
For AI agents
Every tool, the engine's included (backtest_combo, hedge_study, backtest_report, holdings_stress), is plain HTTP on the server: its own route, and POST /api/tools/<name> (GET /api/tools lists them with their schemas). Inputs are validated against described schemas, and every run can be listed, rerun and compared: agent toolkit.
Documentation
- How Optra fits together: the three programs, why they are split, a quote's path through the engine, from an idea to the paper account
- The engine: events and booking, the live process and its threads, restarts and expiry, backtests, what IB sends back, speed, building and testing
- The server and the page: what the server does, the page's views, running it day to day
- Research: the research views, the methods, market data, tools for agents
- Backtest data: the format, converting Databento downloads, replaying paper days, synthetic days
- For coding agents: AGENTS.md
Project status
About 13,000 lines of core C++, 154 GoogleTest cases (concurrency, shutdown and IB paper-account integration among them), ASan and TSan runs, and a P&L regression of the example strategies on every change. Paper trading only; the next steps are multi-day backtests, stocks and lower latency. python-mvp keeps the original hand-written Python implementation the C++ system grew out of.
License
For learning and portfolio use (LICENSE). No commercial use, redistribution or production integration without written permission. Trading carries substantial risk; connecting a live account is at your own risk.
Yorumlar (0)
Yorum birakmak icin giris yap.
Yorum birakSonuc bulunamadi